Useful business guidance

Guides for Kiwi business owners

Straight answers on business funding in New Zealand — from paying off IRD and handling a statutory demand, to second mortgages, bridging finance and funding your next big contract. 34 in-depth guides and counting.

Tax and IRD

GST, PAYE, provisional tax and getting Inland Revenue off your back.

Property-secured lending

First and second mortgages, equity, caveats and bridging.

Boats moored in a Wellington marina with houses on the hills behind
Property-secured lending

How a second mortgage works for business

A second mortgage lets you borrow against the equity in your property without touching your existing bank loan. Here's how it works for New Zealand business owners, from priority and equity to the process and repayment.

Read the guide
Two people reviewing loan documents at a meeting table
Property-secured lending

First vs second mortgage business loan: which suits you?

Both a first and a second mortgage can unlock property equity for your business. The right one depends on what's already owing, your bank loan's terms, how much you need and how you'll repay. Here's how to choose.

Read the guide
A mechanic workshop with tools lining the walls and a car ready for service
Property-secured lending

Using home equity for business

For many Kiwi business owners, the family home is the biggest asset they have. This guide explains how to work out your usable equity, what it can fund, how it compares with other options and how to borrow against your home sensibly.

Read the guide
Rows of grape vines in a Hawke's Bay vineyard with hills in the distance
Property-secured lending

Borrowing against family trust property for your business

Many Kiwi families hold their home or rental in a family trust. That property can still help fund the family business. Here's how borrowing against trust property works, what trustees need to do and how to keep it moving quickly.

Read the guide
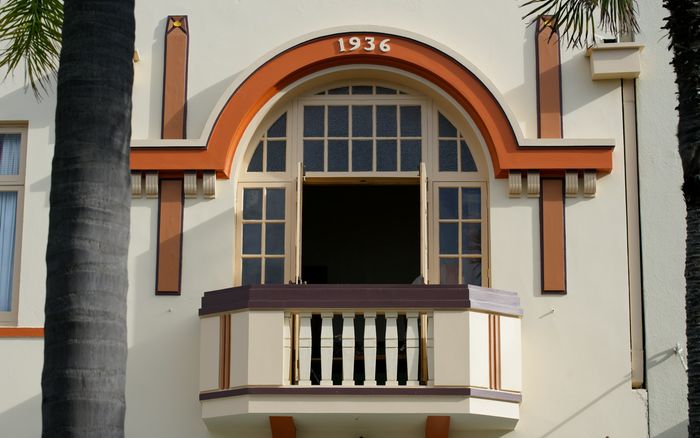
An Art Deco building facade in Napier, Hawke's Bay
Property-secured lending

How much can I borrow against my property?

Your property's value, what you already owe and the lender's maximum LVR set the ceiling on a property-secured business loan. Here's how to work out your usable equity, with worked examples.

Read the guide
Two people reviewing loan documents at a meeting table
Property-secured lending

What is a caveat loan?

A caveat loan is fast, short-term business funding secured against property. Here's how caveats work on a New Zealand title, how they differ from a registered mortgage and when this kind of loan makes sense.

Read the guide
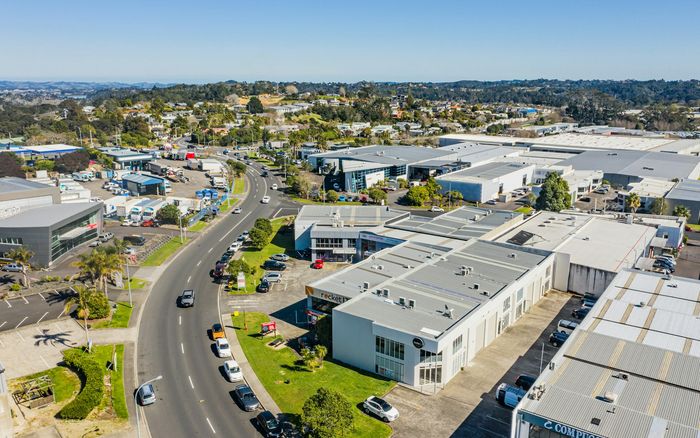
Aerial view of a business park and car parks on Auckland's North Shore
Property-secured lending

Bridging finance explained

Bridging finance covers the gap between needing money now and receiving it later from a sale, refinance or payment. Learn how business bridging loans work in New Zealand, how peak debt is calculated and how to plan the exit.

Read the guide
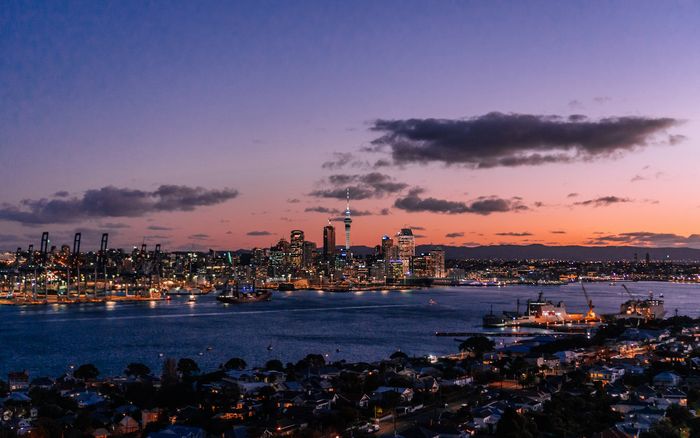
Auckland city skyline across the harbour at twilight
Property-secured lending

How to plan the exit strategy for a short-term business loan

Every short-term business loan needs a clear way out. This guide compares the main exit strategies, shows the evidence lenders look for and helps you build a timeline and backup plan that stands up.

Read the guide

Cash flow and crisis

What to do when the money's tight, demands arrive or the bank says no.

A business owner sitting at a wooden table planning
Cash flow and crisis

Business cash flow crisis: what to do in the first 72 hours

When cash runs short, the first three days decide how much control you keep. This hour-by-hour plan helps New Zealand business owners get the numbers, protect what matters and find the money to close the gap.

Read the guide
A smiling small business owner welcoming customers to her shop
Cash flow and crisis

Alternatives to liquidation for New Zealand businesses

Liquidation ends the company and hands control to someone else. Before you take that step, look at the alternatives, from creditor deals and IRD arrangements to being funded out of trouble with property equity.

Read the guide
Paperwork, a pen and a calculator on a desk
Cash flow and crisis

Statutory demand: what to do if your company receives one

A statutory demand gives your company 15 working days to pay, settle or secure a debt, and only 10 working days to ask the court to set it aside. Here's how to use that time well.

Read the guide
Two business owners shaking hands across a desk
Cash flow and crisis

Bank declined your business loan? What to do next

A bank decline isn't the end of the road. Learn why New Zealand banks turn down business loans, how to find out what went wrong, and the fastest realistic routes to the funding your business needs.

Read the guide
Two people reviewing loan documents at a meeting table
Cash flow and crisis

Refinancing expensive short-term business debt

Daily debits, merchant cash advances and stacked online loans can drain a good business. Here's how to work out what they really cost and refinance them into one loan that suits your cash flow.

Read the guide
Two business owners shaking hands across a desk
Cash flow and crisis

How to talk to creditors and buy time

When cash runs short, the way you talk to creditors decides how much time you get. Here's who to call first, what to say, what to put in writing and how to turn breathing room into a real fix.

Read the guide
A business owner sitting at a wooden table planning
Cash flow and crisis

Late-paying customers and your cash flow

Late-paying customers can sink a profitable business. Here's how to measure the damage, set terms that get you paid, chase firmly without losing clients and fund the gap while the money comes in.

Read the guide
A construction site in Christchurch
Cash flow and crisis

Construction retentions and payment claims: managing cash flow

Retentions and slow progress payments tie up cash that builders and subbies have already earned. Here's how payment claims, payment schedules and the retention rules work, and how to keep cash moving.

Read the guide
Mount Maunganui main beach in the Bay of Plenty on a sunny day
Cash flow and crisis

Managing cash flow in a seasonal business

Busy summers, quiet winters and harvest peaks make seasonal businesses hard to run on cash. Here's how to map your year, build a reserve for the trough and fund the quiet months without panic.

Read the guide

Growth and investment

Contracts, new sites, equipment and buying a business.

Borrowing know-how

How lenders think, what they need and how fast it can happen.

Two people reviewing loan documents at a meeting table
Borrowing know-how

Private lender vs bank vs broker: which is right for your business loan?

Banks, brokers and private lenders all play a role in business lending. Here's an honest look at how each works, what they're good at and when going direct to a private lender makes sense.

Read the guide
A business owner sitting at a wooden table planning
Borrowing know-how

Low doc business loans: what lenders actually need from you

Accounts behind, irregular income or no time for a paperwork marathon? Here's exactly what a low doc business lender needs, what can stand in for financial statements and how to get your application ready fast.

Read the guide
A smiling small business owner welcoming customers to her shop
Borrowing know-how

Business loans with bad credit: how to get a fair hearing

Defaults, arrears, IRD debt or a bank decline don't have to be the end of the road. Here's how lenders really read bad credit, what you can fix, and how property-secured lending can help.

Read the guide
Aerial view of a business park and car parks on Auckland's North Shore
Borrowing know-how

What lenders look at: your business loan checklist

Every lender runs your application through the same basic questions. Learn what they are, how banks and private lenders weigh them differently, and use our checklist to get loan-ready.

Read the guide
A truck driving along a New Zealand highway in evening light
Borrowing know-how

How fast can you get a business loan in New Zealand?

From the first enquiry to money in your account, every business loan passes through the same stages. Here's the timeline anatomy, where the days usually go and how to save them.

Read the guide
A mechanic workshop with tools lining the walls and a car ready for service
Borrowing know-how

Business loans for sole traders: how to borrow as a self-employed Kiwi

Sole traders keep New Zealand running, but lenders don't always make borrowing easy. Here's how sole trader lending works, how to prove your income and how to get loan-ready.

Read the guide
Two business owners shaking hands across a desk
Borrowing know-how

The story behind the name fundU

A name should mean something. Ours hides a smile, a conversation and a word for brilliant, and each one is a promise about how we lend to New Zealand businesses.

Read the guide