
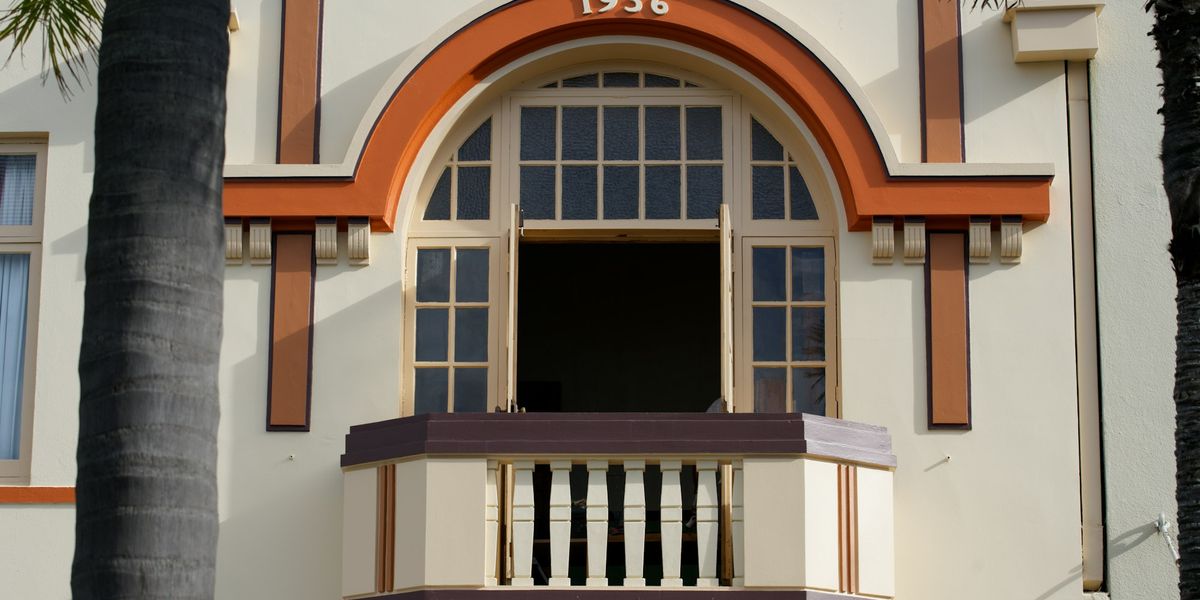
Hawke's Bay is a region of growers, makers and hosts. Its orchards and vineyards feed export markets around the world, its food processors and packhouses keep a large local and seasonal workforce busy, and Napier's Art Deco streets and the Bay's wineries bring visitors back year after year. It's also a region that has been through a lot. fundU offers business loans in Napier and Hastings from $20,000 to $1m, secured on property, with decisions made by our own credit team.
We lend against property in Napier, Hastings and right across Hawke's Bay, from Wairoa in the north through Bay View, Taradale, Havelock North and Clive to Waipawa, Waipukurau and the rest of Central Hawke's Bay. Our central lending team works with you by phone and online, so there's no need to travel.
How is Hawke's Bay business recovering after Cyclone Gabrielle?
Cyclone Gabrielle in February 2023 hit Hawke's Bay harder than almost anywhere. Orchards and vineyards in the Esk Valley and around Pakowhai and Omahu were buried in silt, homes and businesses flooded, and roads, bridges and power were cut. For many businesses, the damage went far beyond what insurance covered.
The recovery has been long. Many orchards had to be cleared and replanted, which means years before trees are fully productive again. Businesses that supply and service growers, from irrigation and machinery firms to packhouses and contractors, felt the drop in spending. Plenty of owners kept going by deferring tax, stretching suppliers and taking on expensive short-term debt.
Today, a lot of those businesses are trading well again. What they carry is the leftover debt. That's where a property-secured loan can help: bringing scattered debts together, paying out IRD and giving the business a clean run.
If creditors are pushing you, talking to them early often buys more time than you'd expect. Our guide on how to talk to creditors and buy time explains how to approach it.
Which Hawke's Bay businesses do we work with?
- Orchardists and horticulture businesses growing apples, pears, stonefruit and vegetables across the Heretaunga Plains.
- Horticulture service firms such as irrigation, machinery, spraying, pruning and picking contractors.
- Wineries and vineyard businesses in the Gimblett Gravels, Bridge Pa, Havelock North and beyond.
- Food processors, packhouses and cool stores in Hastings, Whakatū and Napier.
- Builders, trades and engineers working on repairs, rebuilds, new housing and orchard infrastructure.
- Tourism and hospitality businesses in Napier's Art Deco centre, Ahuriri, Havelock North and wine country.
- Freight and logistics operators linked to Napier Port and the export supply chain.
Our rural and agribusiness page covers the funding challenges growers and rural businesses face.
How do the seasons affect Hawke's Bay cash flow?
Much of the Bay runs to the harvest calendar. Apple and pear picking, stonefruit, squash and the grape vintage all fall roughly between late summer and early winter, and that's when packhouses, contractors and wineries take on crews and spend heavily. The income from export fruit and wine can arrive well after the work is done, sometimes in several instalments.
Hospitality and tourism have their own peak. Summer, the Art Deco celebrations in Napier and the wine country's busy weekends bring visitors in, while winter can be much quieter. Out in Central Hawke's Bay, sheep and beef farming and the businesses that service it follow the lambing, shearing and sale-yard year.
A loan structured with interest-only or capitalised interest terms can carry a business through those gaps. Our guide to seasonal business cash flow has more practical ideas.
What property can I use as security in Hawke's Bay?
We lend against a wide range of Hawke's Bay property:
- Homes and rentals in Napier, Hastings, Havelock North, Taradale and the smaller towns
- Commercial and heritage buildings, including Art Deco premises in central Napier, case by case
- Industrial property in Onekawa, Pandora, Omahu Road and other industrial areas
- Some orchard, vineyard and lifestyle property, case by case
- Property owned by your company, family trust or a supporting family member
Post-cyclone flood designations, silt damage and repairs can affect a valuation, but they don't automatically rule a property out. A registered valuer will look at each one on its merits.
If your home has a bank mortgage you want to keep, a second mortgage can sit behind it. If the property is mortgage-free, we can lend by first mortgage.
What do Hawke's Bay owners use a fundU loan for?
| Situation | How fundU can help |
|---|---|
| Leftover debts and deferred bills from the recovery | Consolidate them into one loan with a clear exit |
| IRD arrears built up during the tough years | Pay Inland Revenue out and stop penalties and interest |
| Expensive short-term finance eating the margin | Refinance it with a single property-secured loan |
| Harvest costs before fruit or grape income arrives | Working capital bridged against property |
| Tourism business preparing for summer and festival season | Cover stock, staff and upgrades ahead of peak trade |
| Commercial building needing repairs or strengthening | Fund the works, secured on the building or other property |
If you're paying too much for short-term debt, our guide to refinancing expensive short-term business debt explains the options, and our business debt consolidation page shows how it works in practice.
Example scenario
A Hastings-based irrigation and machinery business had spent two years supporting orchard clients through the cyclone recovery. Work slowed while clients cleared and replanted, and the company fell behind on GST and PAYE while carrying several costly short-term loans. When a supplier issued a statutory demand, the directors thought they might have to call in a liquidator. Instead, they offered their home in Havelock North, which had a bank mortgage and good equity. We lent $175,000 by second mortgage on capitalised interest terms. The loan paid out the IRD arrears, the supplier and the short-term loans. With orchard clients now replanting and ordering again, the exit was a refinance with their bank once a year of clean trading was on the books.
How does the process work?
- Enquire online or call 09 875 4577. It takes a couple of minutes and doesn't affect your credit score.
- Talk to a lending specialist about the purpose, the property and how you'll repay.
- Get indicative terms if the loan is a good fit.
- Valuation and decision. A registered valuer inspects the property and our credit team decides.
- Your lawyer signs the documents and we settle. Once approved, funding can happen in as little as 24 hours in some cases.
Hawke's Bay businesses have shown remarkable resilience. If you're ready to put the hard years behind you, or to grab the next opportunity, see if you qualify and we'll give you a straight answer.
Frequently asked questions
Can fundU help a Hawke's Bay business still recovering from Cyclone Gabrielle?
Often, yes. Many local businesses are trading well again but still carry debts, IRD arrears or deferred costs from the recovery. A property-secured loan can consolidate those into one facility and give you breathing room. We look at the property, the purpose and a realistic exit rather than one bad year's accounts.
Will flood risk affect a business loan against my Hawke's Bay property?
It can affect the valuation, but it doesn't automatically rule a property out. A registered valuer will consider the property's location, any flood history or risk designation, repairs completed and how easily it would sell. We assess every property case by case and are upfront about what we can lend.
Do you lend against orchards or vineyards in Hawke's Bay?
We consider some orchard, vineyard and lifestyle property case by case, depending on its size, location and marketability. Many owners also use a home or rental in Napier, Hastings, Havelock North or Taradale as security, which can make the process simpler and faster.
Do you lend in Central Hawke's Bay and Wairoa?
Yes. We lend against property in Napier, Hastings and right across Hawke's Bay, including Havelock North, Taradale, Clive, Waipukurau, Waipawa, Ōtāne and Wairoa. There's no office to visit, as our central lending team works with you by phone and online.
A practical next step
Ready to see what's possible?
Tell us what the business needs, when you need it and what property is available. A fundU lending specialist will call you back to talk it through — enquiring is free and won't affect your credit score.